

My Budget Book
OneTwoApps
- 4.8
- 1.13K Reviews
- 100.00K
- Downloads
- $4.99
- Price
Screenshots
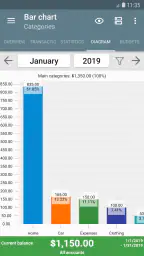
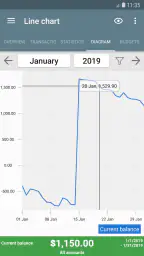
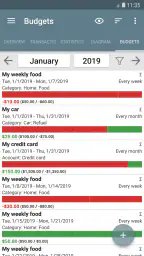
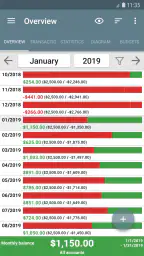
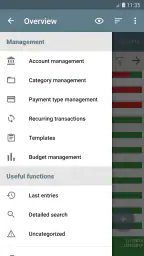
My Budget Book Pros and Cons
Pros
- User-friendly interface
- Comprehensive budget tracking
- Customizable categories
- Syncs with multiple devices
- No ads or in-app purchases
Cons
- No automatic bank sync
- Limited reporting features
- Steep learning curve
- Basic export options
- Lacks cloud backup
 Analysis by All-app
What makes a budget useful to me is not a colorful dashboard but whether I can keep it accurate on a busy day. I want to record a purchase before I forget it, then understand later whether it was a one-off or part of a pattern. My Budget Book is a paid finance app from OneTwoApps that takes a hands-on approach: you enter and organize your own transactions, then use the resulting overview to make decisions. That suits people who want to be involved in the details rather than hand everything over to an automated tracker.
Where the app stands today
The current version is 9.10.1, and the app has been available since February 7, 2012. That long history is useful context, but it does not tell me what changed between releases, so I wouldn’t treat the version number as proof of any particular new feature. What I can say is that the app’s core appeal is clear: it is built around recording income and expenses, categorizing them, and seeing the results in a form that can guide everyday choices.
It has an average rating of 4.8 from around 26,000 ratings, with roughly 1,100 written reviews and over 100,000 installs. Those figures suggest that many users have found a reason to stick with it, though they can’t tell you whether its manual approach will fit your routine. I’d judge that by how willing you are to enter transactions yourself and how much value you place on a budget you can shape around your own timing.
The app costs $4.99, with in-app purchases ranging from $3.49 to $17.99 per item. It is rated Everyone and requires Android 5.0 or later. For me, the practical question is not simply whether a paid app is worthwhile; it is whether the control and visibility it provides are useful enough to justify paying before I know whether I’ll keep up with the habit.
What a manual workflow does well
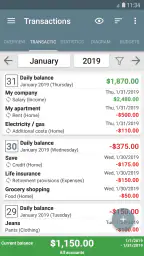
First things first, setting up My Budget Book was a breeze. The app’s interface is user-friendly, and I found it quite intuitive to navigate. You start by entering your income and expenses, which you can categorize. The app supports multiple currencies, which is great if you deal with international finances.
Manual entry can sound like a drawback, but it also makes you pause over each purchase. That brief moment is useful when a small expense would otherwise disappear into a card statement. A practical routine is to enter purchases at the time you make them, or set aside a short daily check-in; waiting until the end of the week can turn a simple ledger into a memory test. I would also keep category names specific enough to reveal habits without creating so many labels that every entry becomes a chore.
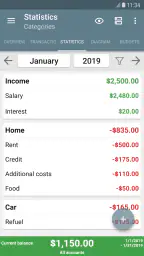
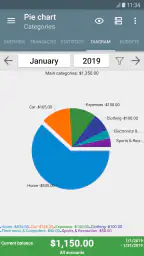
One feature I really appreciated was the ability to set up recurring transactions. This saves a ton of time if, like me, you have regular payments to make. Plus, there’s a nifty option to view a detailed analysis of your finances through graphs and charts. These visuals make it easier to understand where your money is going, and you can quickly spot areas where you might want to cut back.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Recurring entries are most useful when they represent predictable commitments, not estimates that change every month. I’d use them for regular bills or income, then check the actual amount when it differs rather than letting an old assumption shape the picture. This is a small but important distinction: automation inside a manually maintained budget reduces repetitive typing, but it does not remove the need to review what really happened.
Making the schedule fit real life
Another cool feature is the customizable budget periods. You’re not just locked into a monthly cycle; you can set your budget for a week, two weeks, or any other period that suits your financial planning style. I found this flexibility incredibly useful.
That flexibility matters if your pay arrives every two weeks, or if you prefer to review spending weekly instead of waiting for a month-end summary. For example, I might track groceries and transport against a weekly limit while keeping rent and other fixed commitments in a longer view. The trade-off is that a custom period only helps if I check it consistently; changing the time window without a clear routine can make comparisons less meaningful.
For a realistic day-to-day use, imagine buying lunch, picking up a few household items, and paying a bill on the same afternoon. I would enter the purchases under useful categories, let a regular payment follow its recurring schedule, and later check the charts to see whether that day was unusual or part of a pattern. That process makes the app more than a place to store receipts: it turns individual choices into information I can act on, provided I keep the entries current.
Choosing the right kind of budgeting tool
Compared with a basic notes app or spreadsheet, this gives you a purpose-built place to organize transactions and view spending visually, without having to design your own tables and formulas. Compared with a bank-linked tracker, the manual method asks more of you, but it can feel more deliberate and gives you control over what you record. I would favor an automatically populated service if avoiding data entry is the priority; I would choose this style if I want to review each transaction and set my own budgeting rhythm.
It is especially suitable for people who want a personal ledger, are comfortable maintaining it, and value flexible budgeting periods. It may be a poor fit if you expect spending to appear automatically, share a live household budget with several people, or want the app to make financial decisions for you. Before paying, I’d be honest about my habits: a detailed budget that I rarely update is less useful than a simpler method I actually maintain.
Goals, privacy, and the limits to keep in mind
What I love about My Budget Book is how it empowers you to take control of your finances. It’s not just about tracking expenses but also about planning for the future. There’s a feature that allows you to set financial goals, and the app will help you track your progress towards them.
Goals work best when they connect to a concrete decision, such as setting aside money for a planned purchase, rather than being vague targets I never revisit. I’d check progress alongside the spending categories: if a goal keeps slipping, the transaction history may help show whether the issue is an unrealistic target or a category that needs attention. The app can help me monitor that relationship, but I still have to decide what adjustment is sensible.
Security-wise, the app doesn’t require an internet connection, which means your data is stored locally on your device. That's a huge plus if you’re concerned about privacy and data security.
Local storage is a meaningful privacy trade-off, not a complete substitute for good device habits. I’d protect the phone itself and think ahead about how I would preserve my records if I changed devices. This approach can be reassuring if I prefer not to depend on an online account, but someone who needs convenient access across devices may prefer a service designed around synchronization. I would also treat charts as a record of the entries I made, not an independent audit of my finances: missed transactions can make even a polished summary misleading.
What to weigh before settling on it
One question worth asking before choosing it is whether the manual routine will survive your busiest week. If you usually remember card purchases only after several days, try a simple rule: enter them when you get home, and use a brief review to catch omissions. Another is whether your finances fit a personal ledger. Multiple currencies can help when you handle spending in more than one currency, but the important test is still whether you can categorize and review those transactions in a way that makes sense to you.
There is also a difference between tracking a goal and receiving financial advice. The goal feature helps you follow progress, while the decisions about what to save, postpone, or change remain yours. If you need automatic account aggregation, shared household controls, or hands-off recommendations, I’d look for a different kind of finance app rather than expecting a transaction ledger to cover those jobs.
OneTwoApps has continued to maintain the product through its current version, but a release number alone does not establish what has changed or how any future update will affect an existing setup. If you already use it, I’d keep your own budgeting routine steady and check the app’s current release information before relying on a change to a familiar workflow. If you are considering it now, the most useful thing to watch is whether its manual, locally stored approach matches the way you want to manage your records.
My take after weighing the trade-offs
All in all, My Budget Book is a solid choice for anyone looking to get a better grip on their financial situation. Whether you’re a budgeting newbie or a seasoned pro, this app offers tools that are both straightforward and effective. Give it a shot; you might just find it’s the budgeting buddy you’ve been searching for!
Frequently Asked Questions
What is My Budget Book and how does it work?
My Budget Book is a comprehensive financial management app designed to help users track their income, expenses, and overall budget. It offers features such as transaction tracking, budget planning, and financial reporting, allowing users to set financial goals and monitor their progress. The app provides insights into spending habits with graphs and charts, making it easier to manage personal finances effectively.
Is My Budget Book available for both Android and iOS devices?
Yes, My Budget Book is available for both Android and iOS platforms. Users can download the app from the Google Play Store for Android devices and the Apple App Store for iOS devices. This ensures that users can manage their finances on-the-go, regardless of their device preference.
Can I sync My Budget Book across multiple devices?
Currently, My Budget Book does not offer automatic cloud syncing across multiple devices. Users need to manually back up and restore data if they wish to access their budget information on another device. This means that while the app provides robust financial management tools, users must manage data transfer between devices themselves.
Does My Budget Book offer support for multiple currencies?
Yes, My Budget Book supports multiple currencies, making it a versatile choice for users who travel frequently or manage finances in different currencies. The app allows users to set their preferred currency and switch between currencies as needed, helping them maintain accurate financial records regardless of their location.
Is there a cost associated with using My Budget Book?
My Budget Book is a paid app, typically offered at a one-time purchase cost rather than a subscription model. This means users pay once to gain full access to the app's features without recurring fees. The pricing may vary slightly depending on the platform and region, so users should check the respective app store for the current price.


